Amberwood at Holland Gains From Singapore’s Property Market Safeguards
In Singapore’s private residential market, confidence rests on more than an attractive address. It also depends on a regulatory framework designed to encourage financial discipline, temper speculative demand and support a sustainable housing environment. For buyers considering Amberwood at Holland, these safeguards provide context for a purchase intended to serve both lifestyle aspirations and long-term ownership objectives.
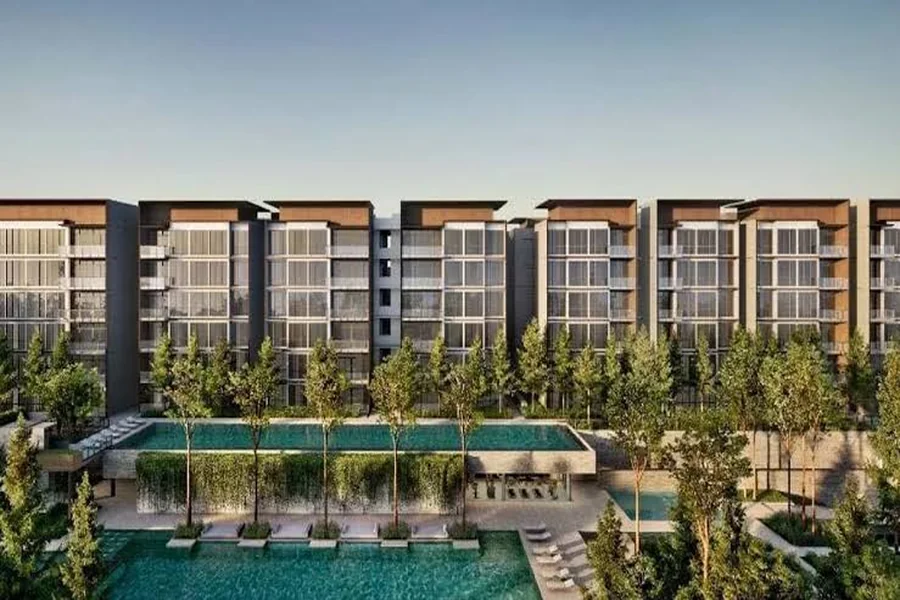
Located at Holland Link near King Albert Park MRT Station, the new condominium by Sim Lian Group sits within this carefully managed market. Its appeal should therefore be considered alongside the policies shaping buyer eligibility, financing and transaction costs. While government measures cannot guarantee capital appreciation or eliminate market risk, they can help create conditions in which purchasers make more deliberate, financially grounded decisions.
How Amberwood at Holland Benefits From Disciplined Demand
Singapore’s cooling measures are intended to moderate excessive demand and discourage behaviour that could destabilise the residential market. Additional Buyer’s Stamp Duty, for example, differentiates acquisition costs according to factors including a purchaser’s residency status and existing residential property ownership. This introduces a substantial consideration for buyers expanding their holdings, rather than purchasing primarily for their own occupation.
For a development such as Amberwood at Holland, this framework can support a purchasing environment shaped more by housing needs, affordability and ownership horizons than by short-term trading expectations. Buyers still need to assess the project on its individual merits, but a market with checks on speculative activity offers a more measured setting for that evaluation. The benefit is not an assurance of rising values; it is stronger discipline around the decision to buy.
Financing Rules Encourage Sustainable Ownership
A premium home should complement its owner’s financial position rather than place it under unnecessary strain. Singapore’s Total Debt Servicing Ratio framework limits the proportion of monthly income that can be committed to debt repayments, subject to applicable rules and exemptions. Loan-to-value limits also constrain borrowing, with the permitted financing dependent on the borrower’s circumstances and prevailing requirements.
Together, these measures encourage purchasers to examine their financial commitments before proceeding. For prospective owners here, that means considering the down payment, stamp duties, mortgage instalments and ongoing ownership expenses as a connected financial picture. This discipline is especially valuable when interest rates, household income or personal priorities change over time.
Financial Resilience Matters Beyond the Initial Purchase
Prudent financing can reduce exposure to repayment stress, although it cannot remove every financial risk. Buyers who retain appropriate liquidity and avoid overstretching may be better positioned to hold their homes through less favourable market conditions. At the individual level, this supports greater flexibility. Across the wider market, responsible borrowing helps limit vulnerabilities associated with excessive leverage and abrupt shifts in sentiment.
Holding Period Rules Reinforce a Longer View
Seller’s Stamp Duty is another safeguard relevant to residential purchasing decisions. Depending on when a property is acquired and subsequently sold, a disposal within the applicable holding period may attract additional tax. Buyers should verify the prevailing rules for their transaction rather than rely on assumptions drawn from earlier policy settings.
This potential cost discourages rapid resale and encourages purchasers to think beyond a short investment window. For Amberwood at Holland, that perspective aligns with evaluating a home for sustained enjoyment: whether its location suits regular journeys, whether the accommodation meets evolving household needs, and whether ownership remains comfortable over time. Cooling measures thus reinforce a more considered approach to both lifestyle selection and financial planning.
Buyer Protections Add Structure to New Launch Purchases
Cooling measures operate alongside safeguards governing the sale of uncompleted private residential properties. Where applicable, Singapore’s housing developer licensing framework, prescribed contractual documentation and project account requirements establish rules around how developments are marketed, sold and funded. These protections introduce procedural discipline into a transaction that typically involves payments made before a home is completed.
For purchasers considering a new condominium by Sim Lian Group, the practical benefit is a regulated purchasing process rather than a substitute for due diligence. Buyers should still review the sale and purchase agreement, approved plans, payment schedule and relevant disclosures with their legal advisers. Regulatory oversight does not guarantee completion, workmanship or investment performance, but it provides an important foundation for understanding contractual rights and obligations.
A Managed Market Supports More Informed Decisions
Singapore’s broader approach combines demand-side measures with land supply planning and ongoing monitoring of housing conditions. Policy settings may change as economic circumstances and market pressures evolve. This responsiveness is relevant to purchasers because residential property is a long-term commitment made within a changing financial and regulatory landscape.
Against that backdrop, Amberwood at Holland benefits from being assessed within an established system of safeguards rather than an unrestricted market. Buyers can weigh its Holland Link setting and proximity to King Albert Park MRT Station alongside financing requirements, acquisition taxes and their intended holding period. Each factor contributes to a more complete assessment of suitability, without assuming that regulation alone makes any particular purchase attractive.
Confidence Built on Prudence Rather Than Promises
The strongest case for government safeguards is not that they remove uncertainty, but that they encourage greater care before ownership begins. For buyers drawn to Amberwood at Holland, cooling measures and purchaser protections provide a framework for matching aspiration with financial readiness. A well-considered purchase remains one supported by independent advice, realistic expectations and the capacity to hold comfortably. Within Singapore’s regulated residential market, that is a foundation for lasting ownership confidence.